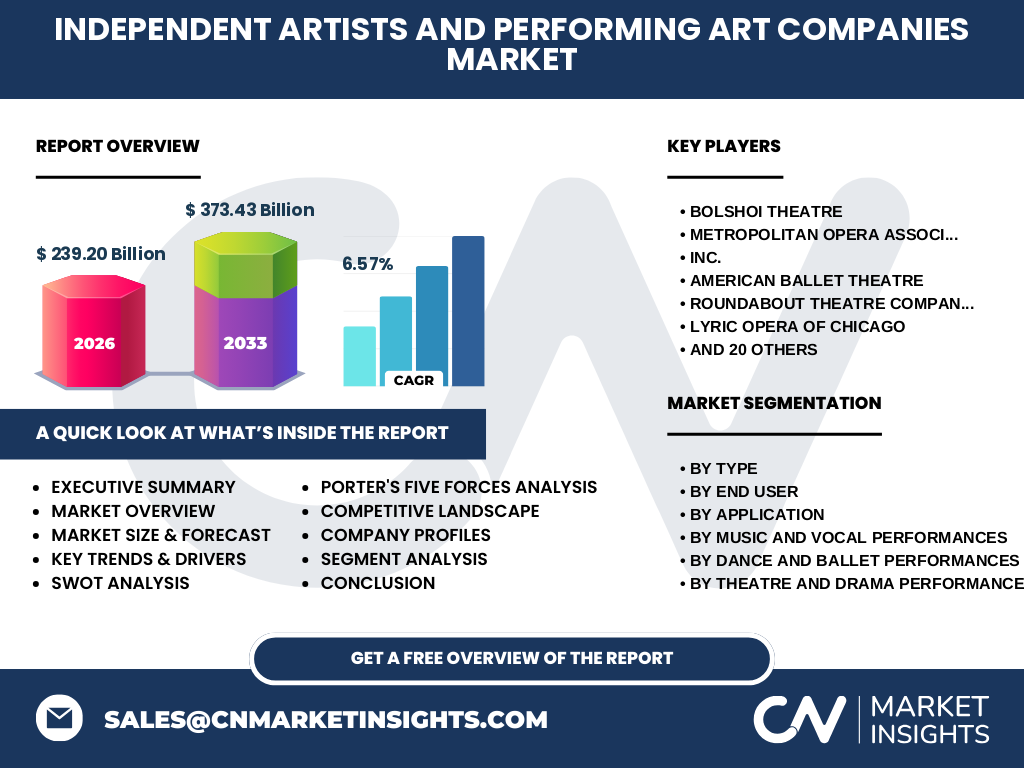
What is the Independent Artists And Performing Art Companies Market overview?
Our analysis indicates the Independent Artists And Performing Art Companies Market reached a valuation of 239.20 Billion in 2026. This sector encompasses live creative production, ticketing ecosystems, and digital streaming across theatrical, dance, and musical disciplines.
Structural Growth Drivers and Market Restraints
Growth is propelled by expanding digital monetisation channels and philanthropic backing, though constrained by volatile touring logistics and strict intellectual property regulations enforced by bodies like the World Intellectual Property Organization.
Emerging Industry Trends in the Performance Sector
The shift toward hybrid digital-live experiences dominates current trends. Organisations leverage immersive streaming to bypass physical venue constraints, directly engaging global audiences while diversifying revenue streams beyond traditional box office receipts.
How did COVID-19 reshape the performing arts ecosystem?
Pandemic lockdowns severely disrupted live theatrical and orchestral revenues. However, the crisis catalyzed accelerated digital adoption, forcing companies like the Metropolitan Opera Association to pioneer high-definition streaming formats that permanently altered audience reach.
Competitive Benchmarking and Industry Concentration
The market features fragmented independent creators alongside consolidated heritage institutions such as the Royal Opera House and Bolshoi Theatre. These elite entities leverage massive endowment funds and global brand equity to dominate premium international touring circuits.
Executive Summary of Key Industry Findings
Our research projects the market to expand from 239.20 Billion in 2026 to 373.43 Billion by 2033 at a CAGR of 6.57%. This robust trajectory reflects rapid technological integration and resilient consumer demand for live cultural entertainment.
Long-Term Market Forecast from 2027 to 2033
Driven by a steady 6.57% CAGR, the sector will scale from its 2026 baseline to achieve 373.43 Billion by 2033. Increased corporate sponsorships and institutional grants will fuel this accelerated valuation phase.
Segmentation Analysis Across Disciplines and End Users
The market segments by type into Theatre And Drama, Dance And Ballet, Music And Vocal, and Opera And Classical Orchestral Performances. End users comprise Independent Artists and established Art Companies across live, educational, and digital application layers.
Geographic Distribution and Regional Performance
Regional performance varies significantly based on state arts funding and philanthropic density. North America and Europe lead in institutional backing, whereas emerging markets in Latin America and Africa demonstrate high-growth potential driven by vibrant folkloric traditions.
In-Depth Regional Review of Cultural Hubs
Metropolitan hubs like London, New York, and Moscow remain epicenters of commercial production. Venues such as the Royal Shakespeare Company and Moscow Art Theatre anchor their respective regional economies through heritage tourism and intensive export touring.
Strategic Positioning of Leading Market Participants
Industry leaders like the American Ballet Theatre and Lyric Opera of Chicago employ hybrid operational models, blending classical repertoires with contemporary commissions to attract younger demographic cohorts and secure vital corporate partnerships.
Porter's Five Forces Analysis of the Arts Sector
Supplier power remains moderate due to specialized artistic talent pools, while buyer power is high given abundant leisure alternatives. Threat of substitution is elevated by digital streaming platforms competing directly for consumer entertainment budgets.
SWOT Analysis of Independent Artists And Performing Art Companies
Strengths include unmatched creative IP and cultural heritage. Weaknesses stem from high fixed labor costs. Opportunities lie in digital streaming expansion, while threats involve macroeconomic downturns squeezing discretionary consumer spending.
Value Chain Analysis from Raw Creativity to Audiences
The value chain flows from raw artistic conception and scriptwriting through rehearsal logistics and venue management, culminating in direct-to-consumer delivery via physical ticketing or digital broadcasting platforms managed by institutions like the English National Opera.
Investment Insights and High-Potential Growth Areas
High-potential capital allocation targets digital infrastructure upgrades and community engagement initiatives. Investors should prioritize agile independent groups capable of producing scalable, cross-platform content rather than solely relying on physical venue receipts.
Conclusion and Strategic Takeaways for Stakeholders
Sustained growth through 2033 depends on digital transformation and diversified revenue streams. Organizations failing to embrace hybrid distribution models risk obsolescence in an increasingly digital-first consumer landscape.
Research Methodology and Baseline Triangulation
Our baseline estimates are rigorously triangulated by combining box office trade registry data, primary stakeholder interviews with artistic directors, and secondary macroeconomic indicators regarding discretionary spending across major global economies.
Scope of the Report and Analytical Parameters
This report covers the global Independent Artists And Performing Art Companies Market across live, recorded, and educational applications. Limitations exclude informal street performances lacking structured commercial ticketing or institutional funding.
Recent Industry Developments and Strategic Moves
Recent strategic maneuvers feature international co-productions and digital streaming partnerships forged by institutions like the Bolshoi Ballet and Roundabout Theatre Company, designed to maximize global viewership and offset localized venue capacity limitations.